
Short answer
Ask what fact the document must prove, why it is needed now, which alternatives are accepted, how to redact unrelated data and when the review will be updated. Do not send passwords, full card numbers or one-time codes.
Start with the exact status
GB-licensed online gambling businesses must verify core identity before allowing gambling. Additional information can still be required later where a legal obligation or newly identified risk genuinely arises.
Likely explanations
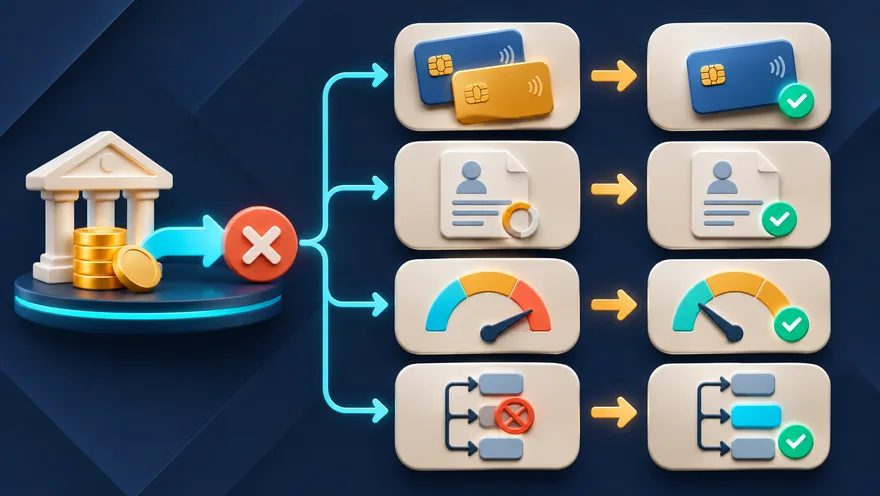
The main categories are core identity was not matched electronically, a payment method needs ownership proof, account data changed, a transaction pattern created a new risk, and source-of-funds evidence is legally required. These are diagnostic categories, not conclusions about a specific account. The operator’s written reason and transaction record are the evidence.
What to do now
Ask what fact the document must prove, why it is needed now, which alternatives are accepted, how to redact unrelated data and when the review will be updated. Do not send passwords, full card numbers or one-time codes.
Evidence pack
Keep the request time, amount, currency, masked destination, status history, transaction reference, relevant terms as displayed on the date, document requests and support replies. Write a short timeline. Do not send unredacted financial data unless the recipient, purpose and secure upload route are clear.
What not to do
Do not create several new accounts or payment destinations, submit altered documents, ask for a way around KYC, disable a protective bank block or keep depositing to “unlock” a payout. Those actions can add risk and make the record harder to follow.
Escalation boundary
Ask for a written final response through the operator’s formal complaints route. The Gambling Commission receives reports and regulates businesses, but it does not decide individual transaction disputes. ADR comes after the operator process, subject to the scheme’s remit.
Diagnostic record
| Field | What to record | Why it matters |
|---|---|---|
| Status | Exact label and screenshot time | Locates the stopped stage |
| Clock | Requested, approved, sent, credited | Separates operator and bank time |
| Reason | Exact written wording | Avoids guessing |
| Reference | Operator and provider IDs | Enables a trace |
| Remedy | Specific correction or payment requested | Makes a complaint actionable |
Practical checklist
- Record the exact status and time.
- Identify the operator, payment rail and receiving account.
- Save both transaction references.
- Check the written time window and currency.
- Escalate with a short evidence-based timeline.
Questions people ask
Should I keep contacting live chat every hour?
No. Ask once for the owner, reason and update time, then use the formal complaint route if the written window is exceeded.
Can support ask for my password or one-time code?
No legitimate payment or verification check needs your password or authentication code.
Is this legal advice?
No. It is an editorial troubleshooting framework; seek independent legal advice for litigation or significant sums.
Continue the route
Sources checked 2026-11-18
- https://www.gamblingcommission.gov.uk/public-register/businesses
- https://www.gamblingcommission.gov.uk/public-and-players/guide/gambling-and-young-people
- https://www.gamblingcommission.gov.uk/public-and-players/guide/age-and-id-verification
- https://www.gamblingcommission.gov.uk/licensees-and-businesses/guide/page/identity-verification
- https://www.gamblingcommission.gov.uk/blog/post/key-issues-and-our-expectations-concerning-account-withdrawals
Editorial note: Availability, fees, limits and processing windows can change. Check the live cashier and current first-party terms. Examples are illustrative and do not predict a result.