
Short answer
A GB-licensed operator must verify age and identity, and it has anti-money-laundering obligations that allow it to ask about the source of funds. So the request itself is legitimate; what should be specific is what is required and why.
The practical objective is therefore not to dispute the principle but to close the list. Ask for the outstanding items as a list, supply exactly those, and record the dates.
A list that shortens round by round is a process. A list that grows after each submission is a holding pattern, and that distinction is the substance of any later complaint.
What is normally checked
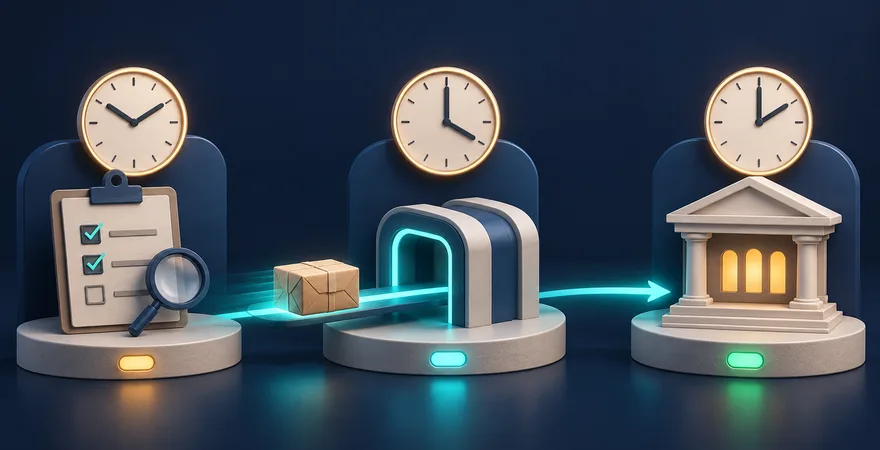
Identity and age, usually from an identity document. Address, usually from a recent document showing your name and address. Ownership of the payment instrument, so that money returns to an account in your name. And, where amounts or patterns warrant it, evidence about where the funds came from.
Those are four separate checks and each can be outstanding independently. Asking which of the four remains converts a vague hold into a finite task list.
Do all of it at registration where possible. Verification completed in advance is the single biggest determinant of how fast a first withdrawal moves.
| Check | Usual evidence | What is enough |
|---|---|---|
| Age and identity | Identity document | A clear, uncropped image of the whole document |
| Address | Recent document with name and address | Date, name and address legible |
| Instrument ownership | Document naming you and the account | Name, account identifier, institution |
| Source of funds | Evidence for the specific question asked | What the stated question requires |
| Contact details | Access to the registered channel | A code or confirmation |
Source-of-funds requests
These are different from identity checks: they ask where money came from, and they are triggered by amounts or patterns rather than at registration. A licensed operator has obligations here, and a specific, documented request is proper.
Answer narrowly. If the question concerns a particular deposit, evidence about that deposit answers it; a complete financial history is more personal data than the purpose requires, and you can ask what specifically is needed.
Record the question and the response with dates. A hold maintained past the published timescale with no named outstanding item is the scenario where the record becomes the complaint.
Uploading so that it counts
Use the operator’s own verification portal. Documents sent through chat or to an address given verbally may not be attached to the account at all, and the most common hidden cause of a long hold is a document that never arrived in usable form.
Photograph the whole document, flat, in good light, with all four edges visible. Cropped images, screenshots of documents and photographs of screens are the three most frequently rejected formats.
Confirm that the upload was accepted rather than merely sent, and keep the confirmation. A documented accepted upload is the answer to a later claim that something is outstanding.
- Upload through the operator’s own portal, never via chat.
- Photograph the whole document with all edges visible.
- Avoid screenshots of documents and photographs of screens.
- Confirm acceptance, not just submission, and keep the confirmation.
- Redact what is not needed, but never the parts that identify the document.
Privacy while complying
You can comply and still limit exposure. Where a statement is requested to prove an account belongs to you, the account name, identifier and date are the relevant parts, and unrelated transactions can be redacted.
Never redact the elements that identify the document or the transaction: references, dates and names. Over-redaction makes the evidence unusable and produces another round of requests.
If you believe the data requested goes beyond the purpose, ask what it is being used for and for how long it will be held. Those are data protection questions and the operator has to be able to answer them.
When the list keeps growing
Keep the two-column record: item requested and date, item supplied and date. Three rows usually make the pattern visible, and the pattern is the argument.
At that point ask once more, numbered, for the complete outstanding list and the decision date, and note the published complaints timescale. If the period passes with no list and no decision, escalate.
The route is the ordinary one: formal complaint, final response, then the named alternative dispute resolution provider, with the record attached.
- Ask for the outstanding items as a list.
- Supply exactly those, through the portal, and record the dates.
- Confirm each upload was accepted.
- Keep the two-column request-and-supply record.
- Escalate on the published timescale if the list never closes.
FAQ
Can a casino hold my withdrawal for documents?
A licensed operator can require identity and, where warranted, source-of-funds evidence. What should be specific is which items are outstanding and why.
Why am I being asked again for the same document?
Usually a quality or format problem, which should be stated. A repeat request with no stated defect is worth querying in writing.
Do I have to send a full bank statement?
Ask what specifically is being verified. Often the account name, identifier and date suffice, and unrelated transactions can be redacted.
Where should I send documents?
Only through the operator’s own verification portal. Documents sent via chat may never be attached to the account.
How long can a verification hold last?
As long as the operator’s published timescale allows. Past that, with no named outstanding item, it is the case to escalate.
Next pages
Sources
- UK Gambling Commission: age and identity verification, checked 18 November 2026.
- Information Commissioner’s Office: your data rights, checked 18 November 2026.
- UK Gambling Commission: Licence Conditions and Codes of Practice, checked 18 November 2026.